The Credit Report: Credit Spreads Stable Despite Wild Week of News
Week of November 16, 2026 – By Larry Holzenthaler, Senior Portfolio Manager, Catalyst Capital Advisors, LLC
Summary
High Yield (HY) saw significant Treasury-driven volatility last week; however, spreads were relatively stable to marginally tighter despite the wild week of news. The Bloomberg High Yield Index returned -0.25% for the week, with spreads tighter by -10 bps. High yield mutual funds and ETFs have seen over $1B of inflows per week for the last three weeks. This would seem to indicate that investors are viewing the rise in yields as an opportunity.
Senior Loan prices were higher by ¼ point on average last week, as the floating rate asset class again provided a harbor from rate-driven volatility. The S&P UBS Leveraged Loan Index returned +0.21%, as spreads tightened by -6 bps. Loan demand across both retail accounts (mutual funds, ETFs) and institutions (CLOs) remains extremely strong, which is not surprising given the threat of higher rates. Last week, loan mutual funds and ETFs also saw roughly $1B of inflows.
Although rates remain a focus, what likely matters the most for corporate credit investors is earnings and fundamentals. So far, earnings remain highly supportive of credit. It feels as though operating results are contributing to a stabilization in credit spreads, which have widened in recent months. For investors looking for an attractive entry point, the backdrop is beginning to look less precarious following the recent volatility.
Thoughts on Credit into Year-End:
With the holidays approaching, investors will begin preparing for allocation shifts coming into 2027. Credit markets remain somewhat on edge given higher rates, which generally translates into higher funding costs for issuers. However, for longer term investors, higher yields and wider spreads are worth noting.
Dispersion in credit remains extremely high – The ratio of CCC HY spreads to BB HY spreads (CCC/BB) is at the widest levels in the history of the high yield bond market, going back to the mid-1990s, at nearly 6X. That should create opportunities for active managers to find mispriced assets in a market where index yields are already fairly high (8.5%).
Technicals are strong and likely improving – Demand for credit remains rather strong. We expect that to continue into year-end, fueled in part by fixed income tax loss harvesting and the relative value of shorter duration assets. Meanwhile, new issue supply (which has already been constrained by higher rates and market volatility) typically begins to taper off into the end of the year as capital markets activity takes a pause into the holidays. Add to that, loans and high yield bonds typically get year-end paydowns, which must be reinvested into the secondary market as new issue activity slows. That typically stabilizes prices into year-end; however, there are clearly always exceptions.
Last but not least, fundamentals – With Q3 earnings nearly complete, results continue to indicate a supportive operating environment for issuers. With the overall credit quality of the high yield market at all-time highs (more BBs, fewer CCCs) and a relatively strong backdrop, we expect default rates to remain quite low. For loans, our view is that investors need to be more selective with an up-in-quality bias, as the loan market is home to more troubled issuers relative to high yield. Within that higher quality cohort, we believe credit losses should be minimal going forward, while floating rate coupons should continue to increase as the Fed brings rates higher.
Chart of the Week: An argument can be made that yields in the high yield and loan market are poised to provide “equity-like returns” with less volatility, less risk, and higher current income. For traditional fixed income investors, realistically the only scenario that would deliver outperformance versus credit is a near term U.S. recession.
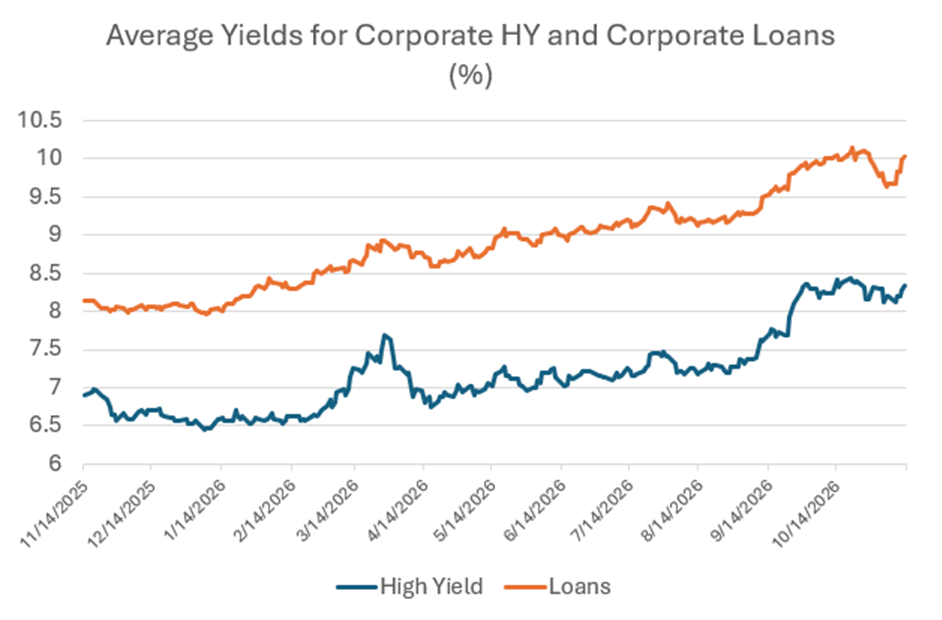
Source: Bloomberg, as of 11/13/26. Bloomberg US Corporate High Yield Index.
Important Disclosures
This commentary is provided by Catalyst Capital Advisors LLC, a registered investment adviser (“Catalyst”), and is for informational purposes only. Registration with the U.S. Securities and Exchange Commission does not imply a certain level of skill or training. This material does not constitute investment, legal, or tax advice. It is not an offer to sell or a solicitation of an offer to buy any security or interest in any fund or strategy, and it should not be relied upon in making an investment decision. Advisory services are offered only pursuant to a written agreement and/or offering document, including a fund prospectus, if applicable. Additional information about Catalyst, including its fees, services, and conflicts of interest, is available in its Form ADV Part 2A, which is available upon request or at adviserinfo.sec.gov. The views expressed are those of the author as of date indicated, are subject to change without notice and may not reflect the views of Catalyst as a whole. Information has been obtained from third-party sources believed to be reliable, but its accuracy and completeness are not guaranteed.
Risk Considerations: High yield bonds and leveraged loans are below investment-grade and are speculative. Such securities carry greater risk of default, price volatility, and illiquidity than investment-grade securities, and investors may lose some or all of their principal. Senior secured status does not eliminate the risk of loss, and recoveries in default may be lower than historical averages. Loans may have extended settlement periods and limited secondary market liquidity. Securities trading at a discount to par may continue to decline, and a discount does not indicate that a security is undervalued or will return to par. These investment are not suitable for all investors. Past performance and historical default or recovery rates are not indicative of future results.
Index Information: Index returns are for illustrative purposes only. They do not reflect fees, expenses, or transaction costs, and do not represent the performance of any account, fund or strategy managed by Catalyst. Indices are unmanaged and cannot be invested in directly. Bloomberg® and the Bloomberg US Corporate High Yield Index are trademarks of Bloomberg Finance L.P. and are used under license. S&P UBS Leveraged Loan Index data is provided by S&P Dow Jones Indices LLC and/or its affiliates.
Conflicts: Catalyst and its affiliates may serve as investment adviser to, and/or sponsor, funds that invest in the asset classes discussed. Catalyst, its personnel, and its client accounts may hold, buy, or sell positions in these asset classes at any time, including in a manner inconsistent with the views expressed, and Catalyst may benefit if the market conditions described materialize.
Forward-Looking Statements: This material contains forward-looking statements, including views on market conditions, valuations, credit fundamentals, and potential opportunities in the high yield and leveraged loan markets. Forward-looking statements can often be identified by words such as “expect,” “anticipate,” “opportunity,” “believe,” “may,” “should,” and similar expressions, or by characterizations of current market conditions as temporary or dislocated. These statements reflect the author’s current views and assumptions as of the date indicated. They involve known and unknown risks and uncertainties that could cause actual results to differ materially from those expressed or implied. Such risks include changes in interest rates, economic conditions, default and recovery rates, credit spreads, market liquidity, trade and tariff policy, and investor sentiment. There is no assurance that current discounts to par will narrow, that market conditions described as dislocated will normalize, or that any opportunity described will be realized. Catalyst undertakes no obligation to update or revise any forward-looking statement, whether as a result of new information, future events, or otherwise.
Investors should carefully consider the investment objectives, risks, charges and expenses of the Catalyst Funds. This and other important information about each Fund is contained in the prospectus, which can be obtained by calling 866-447-4228 or at www.CatalystMF.com. The prospectus should be read carefully before investing. The Catalyst Funds are distributed by Northern Lights Distributors, LLC, member FINRA/SIPC. Catalyst Capital Advisors, LLC is not affiliated with Northern Lights Distributors, LLC.